
Firsthand perspective on small, steady change
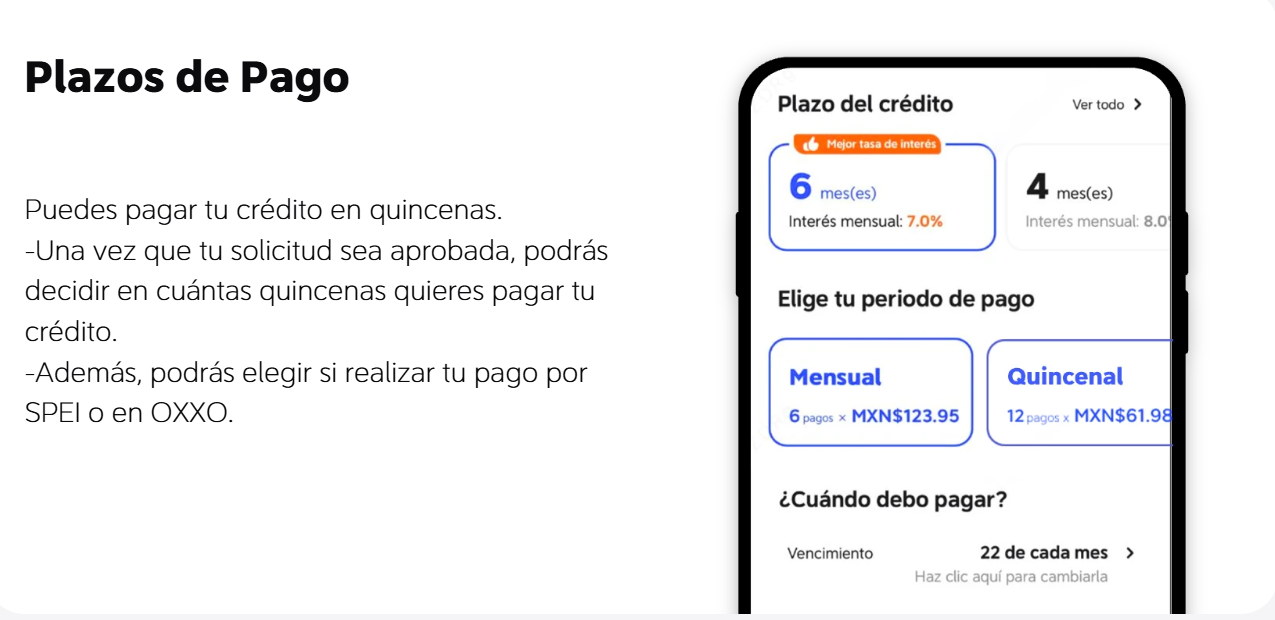
I’ve watched how wallets slimmed down over the years, from leather bulges to a single screen, and I still prefer practical fixes that honor everyday routines. What matters to most people is predictable control — a digital card that lets you split a grocery run into manageable installments or pull a short-term credit line without a stack of forms. For readers exploring options, a sensible first step is to compare simple offers like didi prestamos against what their bank already gives, because clarity beats flashy marketing every time.
How a user-centric product changes daily habits
Good design hides complexity. When a digital wallet delivers a virtual card that behaves like plastic but with clearer spend limits and instant transaction alerts, daily friction drops. People start using credit the way they use a tool — for planning meals, fixing a small appliance, paying a vet bill — rather than treating credit as a looming obligation. The difference shows up in fewer missed payments and less stress about interest accrual.
What the technology actually does for you
Under the hood, a few precise features make the experience reliable: tokenization to protect card numbers, KYC processes that happen fast, and APIs that let apps show balances and approve instant installments. Those industry terms might sound technical, but they create two plain benefits — safer purchases and clearer account control.
Security isn’t theater. Tokenization means your card details aren’t passed around; that matters when you use public Wi‑Fi or tap in a busy plaza — think Mexico City metro rush hour after 2020, when contactless options gained real traction. — small conveniences add up into confident, everyday use.
Common mistakes and sensible alternatives
People often misuse online credit when they treat it like free money. The usual errors are stretching a credit line too thin, ignoring the true cost of interest, and not checking how installments affect available credit for emergencies. Safer alternatives include conservative short-term credit from a trusted service, sticking to fixed monthly installments, or keeping a small emergency fund to avoid rolling balances.
For those comparing solutions, consider mainstream creditos en linea and traditional bank cards side by side. Check forgiveness windows, repayment flexibility, and whether the provider offers clear step-by-step statements. Those factors predict whether a product will help you, not hurt you.
Practical checklist for everyday use
Adopt a few concrete habits and you’ll feel the gain: use a virtual card for subscription management, set notifications for every transaction, and choose installment plans that align with predictable income dates. Keep one low-limit card reserved for recurring bills — that prevents accidental overspend and preserves your broader credit line for genuine needs.
Three golden rules for selecting the right tool
1) Transparency: demand clear terms on interest rates and any fees, expressed in straightforward monthly amounts rather than buried percentages. 2) Flexibility: prefer options that allow small, penalty-free early repayments and let you pause or restructure if income changes. 3) Security and support: pick a provider with tokenization, quick KYC, and reachable customer service who explain things in plain language.
Final thought
After decades of watching payments evolve, I value systems that let people manage day-to-day life without extra worry. The practical value sits in predictable repayment, secure virtual cards, and tools that map to real monthly cash flow — and that’s what makes a provider useful in practice, not just on paper. DiDi Finanzas fits naturally into that description for many users, a quiet solution that helps people keep the lights on and the small pleasures coming — honest, manageable finance. –