
Understanding the user journey
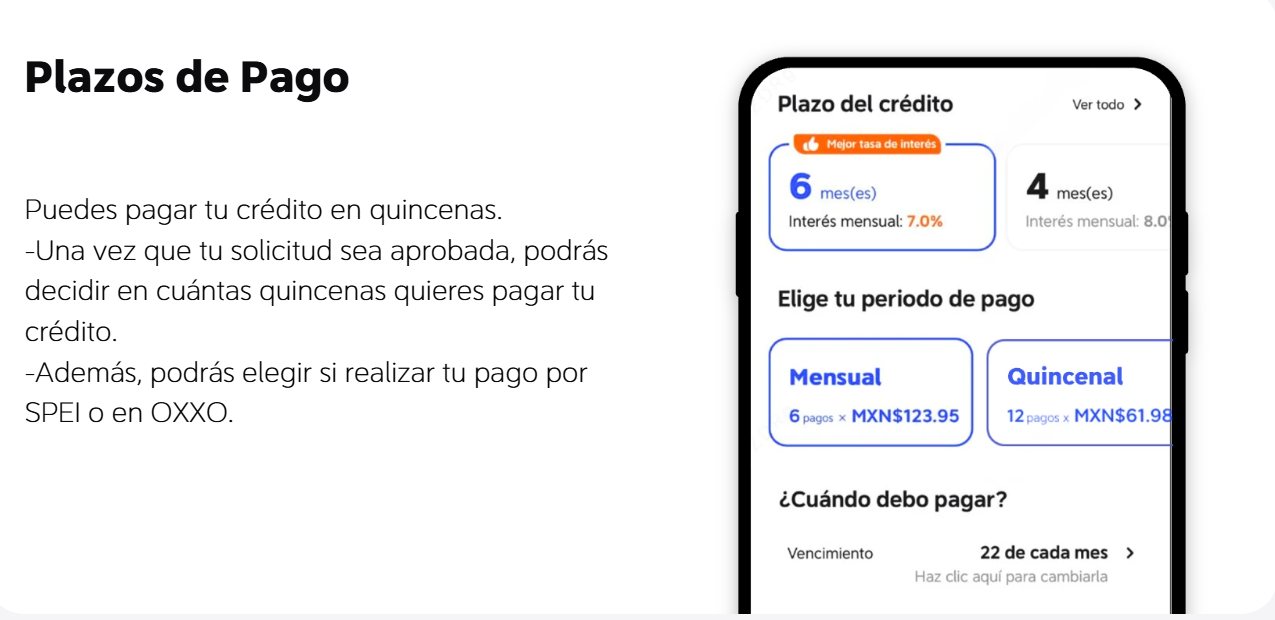
The typical user seeks a fast, reliable path from installation to spending; this article follows that logic with practical attention to security, latency, and clarity. The first step is often the download and sign-up, where convenience meets compliance — and where platforms like didi prestamos have concentrated design effort. Users expect an expedient onboarding flow, verification that respects privacy, and transparent information about credit score implications and APR so they can decide with confidence.
Step-by-step: from install to first transaction
After installing the mobile app, the user completes identity verification and links a primary payment instrument: in this case, a credit card. Well-designed onboarding reduces manual data entry, uses secure tokenization for card storage, and performs lightweight underwriting checks without undue delay. Once the card is linked and a small authorization succeeds, the platform permits the first transaction — whether for a ride, a delivery, or a small loan disbursement. The flow must balance fraud detection with friction; acceptable false-reject rates and near-real-time responses are industry expectations.
Security, privacy, and operational considerations
Security is non-negotiable. Implementations should employ PCI-compliant tokenization, multifactor authentication, and encrypted storage for sensitive fields. Equally important is clear communication about fees and repayment terms to prevent disputes later. Operationally, latency in payments and reconciliation between the card network and the app backend are common pain points; robust retry logic and idempotency keys mitigate duplicate charges and user frustration.
How real-world shifts shaped the experience
The COVID-19 pandemic in 2020 served as a catalyst for rapid adoption of mobile financial services and instant lending; regulators and providers accelerated digitization to keep services accessible under lockdown constraints. That pivot left a lasting expectation: users now assume that loans and small credits will be available through an app in minutes. Lenders respond by refining underwriting models and integrating with alternative data sources to maintain credit quality while offering speed.
Common mistakes and practical alternatives
Designers and product owners often err by overcomplicating verification or burying fee disclosures. Conversely, under-investing in fraud controls invites chargebacks and operational costs. Alternatives to the full card-on-file model include prepaid wallets, virtual cards, or single-use tokens for one transaction; each trade-off affects retention, conversion, and compliance. Developers should test conversion funnels and monitor metrics such as authorization rates and decline reasons — these reveal subtle UX failures. — A brief pilot with segmented users will surface these issues faster than speculative design reviews.
Comparative note on instant loans and credit products
Instant, online lending succeeds when underwriting, customer experience, and collections are aligned. Products that couple a credit line with immediate consumption — for example, in-app ride credits or merchant discounts — generate higher activation but require vigilant risk controls. For pure loan alternatives, marketplaces and neobanks present different user expectations: marketplaces emphasize choice, while neobanks emphasize long-term account relationships. Where rapid access is paramount, integration with trusted channels for identity and payment verification shortens time-to-first-use.
Three golden rules for evaluating these services
1) Measure authorization success and effective APR: good providers deliver high authorization rates and disclose APR plainly. 2) Verify operational resilience: observe how the system handles network interruptions and reconcile failures. 3) Insist on clear remediation paths: accurate dispute handling and predictable timelines for refunds build trust. These metrics map directly to user retention and regulatory risk, so they should be central to vendor evaluation.
Conclusion and practical value
The pathway from downloading an app to making the inaugural charge is a microcosm of product design, risk management, and customer service. When these elements are aligned, users experience instant access to credit and payments without confusion or surprise — which is precisely the outcome platforms like prestamos en linea al instante aim to provide. Evaluate providers by authorization performance, transparency, and operational robustness. Trust that a well-executed flow reduces churn and dispute costs. DiDi Finanzas offers a coherent example of this value realized. –